Cheapest Education Loan Interest Rates in India 2026: Compare Top Banks
Higher education is becoming expensive in India. College fees are only one part of the total cost. Students may also need money for a hostel, books, a laptop and travel.
An education loan can help cover these expenses. However, the wrong loan can create a heavy repayment burden after graduation.
This is why students and parents should compare the cheapest education loan interest rates in India before applying.
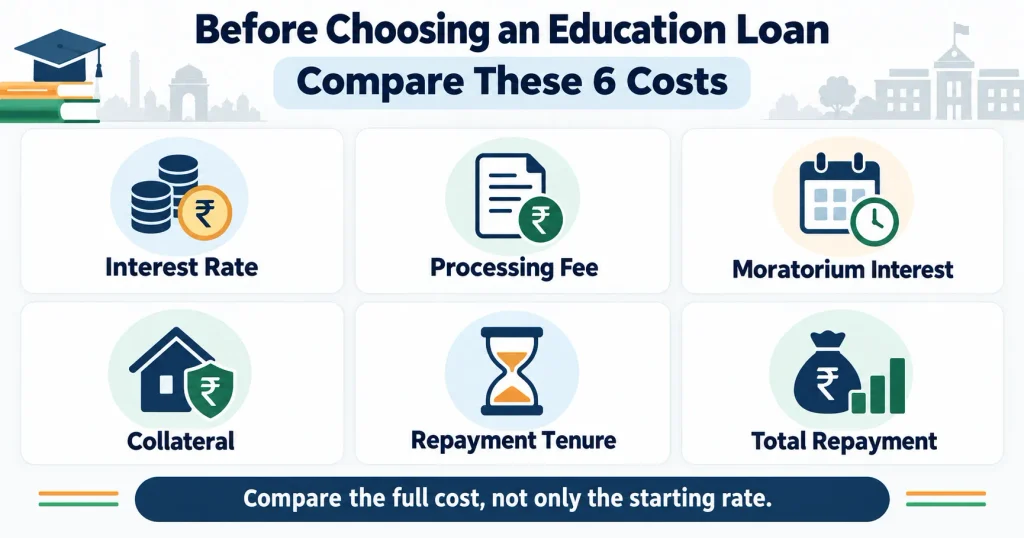
The interest rate is important. Yet it is not the only factor. You must also check the processing fee, moratorium period, collateral and total repayment amount.
Important: The rates in this article were checked in September 2026. Banks can revise their rates at any time. Your final rate will depend on the course, institution, loan amount and applicant profile.
Table of Contents
Cheapest Education Loan Interest Rates in India: Quick Comparison
Several banks offer lower rates to students admitted to selected premier institutions.
| Bank or Scheme | Starting Interest Rate | Best Suited For |
|---|---|---|
| SBI Special Education Loan Offer | 6.75% p.a. | Eligible students at selected premier institutions |
| Bank of Baroda Premier Institution Loan | 6.85% p.a. | Students at approved premier institutions |
| Union Bank PM Vidyalaxmi AAA Category | 7.10% p.a. | Eligible students at top-rated institutions |
| SBI Scholar Loan | 7.25% p.a. onwards | Students at institutions listed by SBI |
| SBI Global Ed-Vantage | 8.30% p.a. | Students planning to study abroad |
| Other Education Loans | Around 8% to 15% p.a. | Regular courses and institutions |
These are starting or scheme-specific rates. Every student may not qualify for the lowest advertised rate.
Ask the bank for a personalised loan offer. Read the sanction letter before making a final decision.
Which Bank Offers the Cheapest Education Loan?
There is no single cheapest bank for every student.
SBI was offering a special rate starting from 6.75% per annum for eligible students at selected premier institutions. This was a limited-period offer available until September 30, 2026, unless extended.
Bank of Baroda offers education loans for students at approved premier institutions from around 6.85% per annum.
Union Bank offers rates starting from 7.10% per annum under the PM Vidyalaxmi scheme for eligible institutions in its highest category.
These low rates are not available for every college. The bank will check your institution, course and loan amount before offering a final rate.
SBI Education Loan Interest Rate
SBI has different education loan schemes.
The SBI Scholar Loan is meant for students admitted to selected premier institutions. Its rates start from around 7.25% per annum.
SBI Global Ed-Vantage is designed for students pursuing full-time education abroad. Its advertised rate is around 8.30% per annum.
SBI also offers regular student loans for studies in India and abroad. The rate depends on the scheme and borrower’s profile.
SBI loan rates can differ by product. For example, a student loan is different from an SBI Pension Loan in India. Students should apply under the correct education loan scheme instead of using a personal-purpose loan for college expenses.
Bank of Baroda Education Loan Interest Rate
Bank of Baroda offers separate schemes for studies in India and abroad.
Its education loan for eligible premier institutions starts from around 6.85% per annum.
The final rate can depend on:
- Institution category
- Course
- Loan amount
- Collateral
- Student profile
- Available concessions
Check whether your college appears on the bank’s approved institution list before applying.
Union Bank Education Loan Interest Rate
Union Bank offers special education loan rates under the PM Vidyalaxmi scheme.
Rates for eligible institutions start from:
- 7.10% for the AAA category
- 7.25% for the AA category
- 7.40% for the AA/A category
- 8.10% for the BBB category
- 8.50% for the BB category
These categories are decided by the bank. A higher-ranked institution may qualify for a lower rate.
Different rates apply to regular education loans and other Union Bank schemes.
Why Education Loan Rates Differ
Two students applying to the same bank may receive different rates.
Banks consider several factors before approving a loan.
Institution and course
Students admitted to recognised or premier institutions may receive better terms.
Banks also consider the course and its employment prospects. Professional and job-oriented programmes may have an advantage.
Co-applicant’s credit profile
A parent, guardian or spouse usually joins the loan as a co-applicant.
A good credit score and stable income can improve the application. Existing debts or missed payments can affect the offer.
Loan amount
A large education loan may come with stricter conditions. The bank may ask for collateral or a family contribution.
Collateral
A secured education loan requires an asset such as property or a fixed deposit.
Secured loans often have lower rates. They may also allow students to borrow a higher amount.
Available concessions
Some banks offer a concession to female students. A concession may also be available when interest is paid during the study period.
Ask the bank about these benefits before signing the loan agreement.
Secured vs Unsecured Education Loans
A secured education loan requires collateral. An unsecured loan does not.
| Feature | Secured Education Loan | Unsecured Education Loan |
|---|---|---|
| Collateral | Required | Not required |
| Interest rate | Usually lower | Usually higher |
| Loan amount | Can be higher | May be limited |
| Processing | Requires asset verification | May be faster |
| Risk | Collateral is at risk | No asset is pledged |
An unsecured loan may look easier. However, it can cost more.
Compare the total repayment of both options. Do not decide based only on convenience.
How Much Difference Can 1% Make?
Consider an education loan of ₹10 lakh for 10 years.
At an 8% annual rate, the approximate EMI would be ₹12,133.
At a 9% annual rate, the approximate EMI would be ₹12,668.
The difference is about ₹535 per month. Over 10 years, you could pay more than ₹64,000 extra.
These figures are only examples. The actual cost may be higher if interest accumulates during the moratorium.
What Is the Moratorium Period?
The moratorium is the period before regular EMI payments begin.
It usually includes the course duration and an extra six months or one year.
However, the moratorium is not always interest-free. Interest may continue to build during this period.
If the unpaid interest is added to the principal, your EMI will increase.
Ask the bank whether you can pay simple interest while studying. This can reduce the repayment burden later.
Costs You Should Compare
The lowest interest rate does not always mean the cheapest loan.
Check these costs before applying:
- Processing fee
- Legal and property valuation charges
- Loan insurance premium
- Margin money
- Late payment charges
- Prepayment conditions
- Foreign exchange costs for overseas studies
Students may also need to buy a computer for their course. Families planning this expense can review whether laptop prices may increase by 5–10% before finalising the total amount required.
Ask every bank for a written cost sheet. It should show the rate, EMI, fees and total repayment.
How to Choose the Right Education Loan
First, calculate the actual amount required. Include college fees and essential study expenses.
Next, collect offers from at least three banks.
Compare:
- Final interest rate
- Fixed or floating rate
- Monthly EMI
- Total repayment
- Processing fee
- Moratorium rules
- Collateral requirement
- Margin money
- Repayment tenure
- Prepayment conditions
Do not borrow the maximum amount simply because the bank approves it.
The future EMI should remain affordable. Your family should also keep some savings for unexpected expenses. You can use our Emergency Fund Calculator for Indian Families to estimate a suitable financial buffer.
Documents Commonly Required
Banks generally ask for:
- Admission letter
- Course fee structure
- Academic records
- Aadhaar and PAN
- Address proof
- Student photographs
- Co-applicant’s income proof
- Recent bank statements
- Collateral papers, if required
- Passport and visa for overseas studies
The bank may request additional documents based on the scheme.
Common Mistakes to Avoid
Do not select a loan only because it shows the lowest starting rate.
Do not ignore the processing fee and moratorium interest.
Check the co-applicant’s credit report before applying.
Avoid submitting applications to too many banks at the same time.
Read the sanction letter carefully. Make sure the offered rate matches what the bank representative promised.
Never pay an unknown agent for guaranteed approval. Banks decide approval after checking the application.
Frequently Asked Questions
Final Verdict
The cheapest education loan interest rates in India are generally available to students admitted to selected premier institutions.
SBI, Bank of Baroda and Union Bank offer competitive starting rates under special schemes. However, the lowest advertised rate may not apply to every student.
Compare at least three loan offers. Check the rate, fees and moratorium conditions. Also calculate the total repayment amount.
Choose a loan that meets your education needs without creating an unmanageable EMI after graduation.
Disclaimer: This article is for general educational purposes only. Rates and loan conditions may change. Verify the latest details directly with the bank before applying. Unifitein.com does not provide loans or guarantee approval.
Hi, I’m Aditya Verma, a tech writer and digital content creator with a passion for exploring technology, apps, online tools, finance, education, and trending topics. I create well-researched and practical content that helps everyday readers understand useful information in a simple and easy-to-follow way.